Quick Verdict: Will Prop Firms Survive Until 2030?
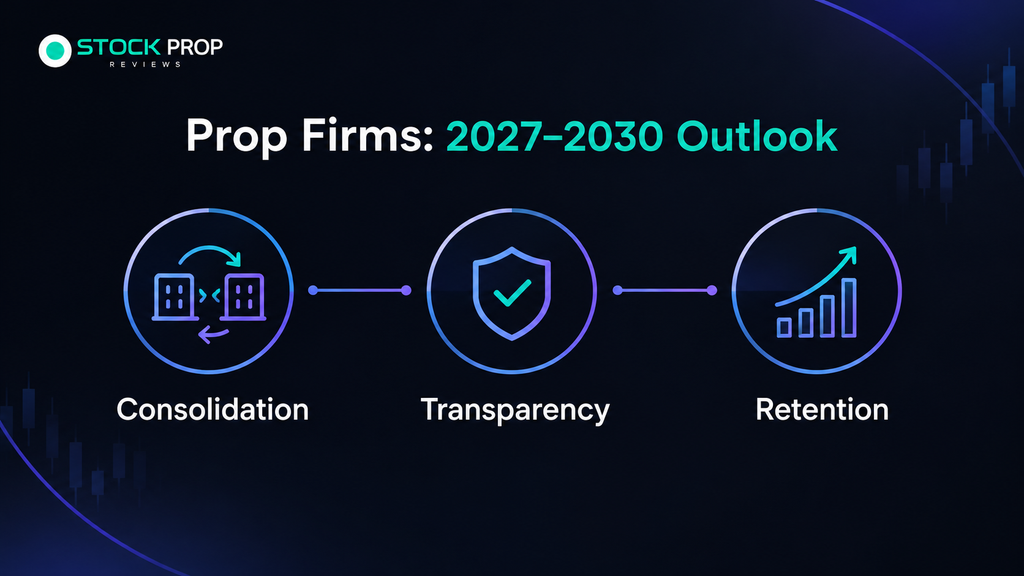
Proprietary Firm Blow Up or Consolidation: 2027-2030 The prop firms will almost certainly be part of the trading industry, but inevitably some providers will shut down, merge, or adjust their business models in the face of competition, operating costs, and evolving regulatory expectations.
The question is not whether all prop firms will survive. The question is whether firms can create viable firms with transparent rules and reliable operations with fair opportunities to earn their rewards.
It isn’t for seasoned forex and futures traders, equity traders wanting to test if prop firms would be viable for them in the long term, or aspirants for funded trading. It is not an outlook for risk-free success trading or guaranteed income.
The five risks to trading terminal taxes are tech changes, business sustainability, payout trust, regulation changes, and trader retention. These factors will decide who can survive and who will struggle to compete.
Why the Prop Firm Industry May Change by 2030
Prop firms typically have their own trading programs and tests that traders must pass to be able to meet certain risk and performance criteria. The trading may be simulated, and payouts may be tied to contractual performance conditions rather than profits from trading in a live market, depending on the provider.
This distinction is important in that the business model accounts for how a firm earns its money (as well as in what manner risk is managed and payouts occur).
“After previous contractions in the market, the thinning of the herd continues, with some of the flailing ones taking up operational weaknesses,” comments Traders’ preview of the industry in August 2026. The estimates of closures are not a full census of the industry and vary, but the risks they represent are worth noting. The traders’ industry forecast might give us some other context.
Three developments are particularly noteworthy.
1. Consolidation Could Reduce the Number of Firms
“The industry may transition into fewer companies with an increased infrastructure and payment and more management,” he said.
The smaller firms may be lost to payment processors, may be charged stiffly for technology, or may be unable to provide the support for quality of service or account growth. Cheap trials and bloated account sizes can be lots of attention but not a sustainable operating model for a provider.
For instance, a fictitious business dependent on assessment fees. If advertising costs increase or customers cease buying new products, then revenues can suddenly drop. It could raise prices, alter its product line, reduce costs, or close down.
Bigger is not necessarily better or safer. A large provider may experience financial stress, operational failure, or dispute. Concentrate on the company’s behavior and contract rather than the brand.
Consolidation can limit competition even further. With fewer providers, there’s less choice, and less competition for their pricing. So not only is the industry shrinking, it’s becoming more secure.
2. Regulation and Compliance May Become More Important
Prop firms do not have universal rules. Actual contracts/jurisdiction/services of a business may be subject to local law.
Some are organized; others are simulated. However, traders shouldn’t assume all firms regulate this way.
This may result in more rigorous requirements on advertising claims, customer verification, payout terms, and dispute resolution by 2030. But how much and when regulation will change is not yet clear.
The expectations can also be industry-set standards. The Financial Commission offers voluntary certification to clarify and resolve disputes. However, the certification is voluntary and is not a replacement of a government authorization and is not an endorsement of the financial solvency of an entity.
Traders should check the claims for themselves. To check the legal entity with which the contract is; whether the registration/authorization is as claimed; and what such status really entitles the company to do.
3. Trader Retention Could Become More Valuable Than Challenge Sales
A company that thrives on challenges may charge itself too much for the acquisition of new customers and a very low markup of traders retained by challenges.
That’s not to say that all firms survive by losing assessments. What this means is that a business model relying on repeated sales may provide different incentives than a company interested in ensuring long-term relationships with customers.
Imagine a trader who takes a test, earns a bonus, and trades within the risk limits of the program. If the trader finds a company with clear rules, fast support response, and reliable account management, he or she may stick around longer.
But retaining them is not the same as being able to sustain that retention. A firm must still manage operating costs, have appropriate risk management, and fulfill its contractual obligations.
Sustainable business will nearly achieve competitive advantage as much or more by retention than by generous promos.
What Will Separate Sustainable Prop Firms From Vulnerable Ones?
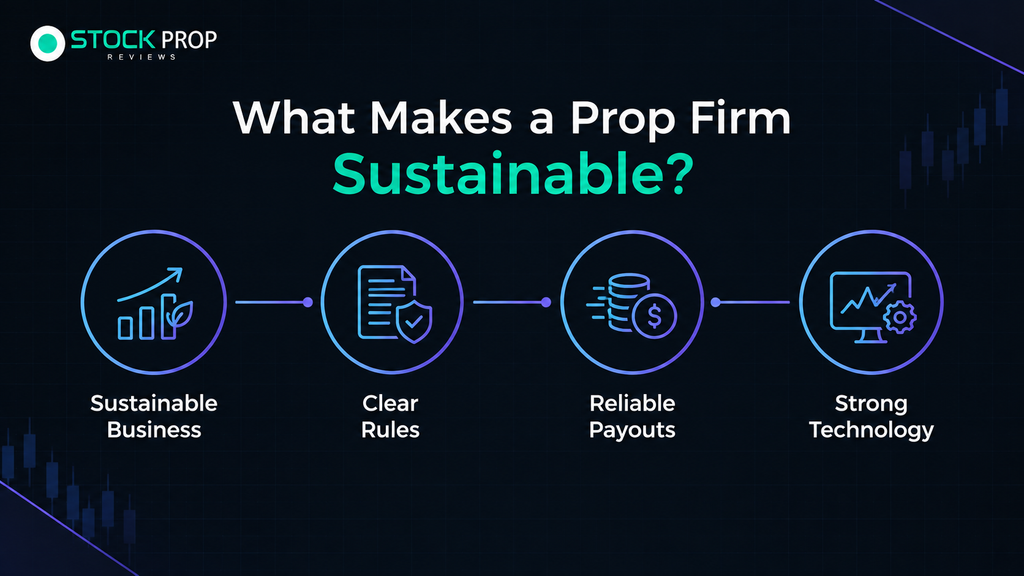
By 2030, a firm’s operational quality may matter more than its advertising budget. Traders should examine the following factors before paying for an evaluation.
| Factor | More encouraging sign | Potential warning sign |
| Business model | Controlled costs and a sustainable revenue strategy | Heavy dependence on constant new challenge sales |
| Payout operations | Clear eligibility rules and documented processing procedures | Repeated unexplained delays |
| Trading rules | Accessible rules and clear enforcement | Ambiguous restrictions or inconsistent decisions |
| Technology | Reliable platforms and contingency planning | Frequent outages without meaningful communication |
| Legal transparency | Verifiable ownership and accurate status claims | Unclear ownership or unsupported regulatory claims |
| Customer support | Documented complaint and escalation processes | Unresolved disputes and inaccessible support |
These are indicators for due diligence, not a formula for predicting a company’s survival. Even a transparent business can encounter unexpected financial or operational difficulties.
How Technology Could Change the Industry
Automated monitoring is already useful in identifying the breaching of trading limits and in identifying fund drainage and suspicious trading activity. Additional developments might improve their consistency and speed.
AI could help firms discover patterns, e.g., sudden increases in position size after losses, or a history of breach of risk limits. The right tools can also improve performance reporting and enable traders to learn from mistakes.
However, automated enforcement comes with risks. If a strategy operates outside of normal account patterns, a monitoring system could misidentify legitimate trading activity.
For instance, where a trader implements a strategy holding positions over volatile sessions. An algorithm automatically marks the activity as dubious and suspends the account time being. If the firm does not explain its decision, or offer an adequate appeal process, the trader could suffer an unjust outcome.
With proper human review, clear rules, and meaningful explanation, technology will serve as reinforcement in the industry.
Which Prop Firm Business Models Are Most Likely to Survive?
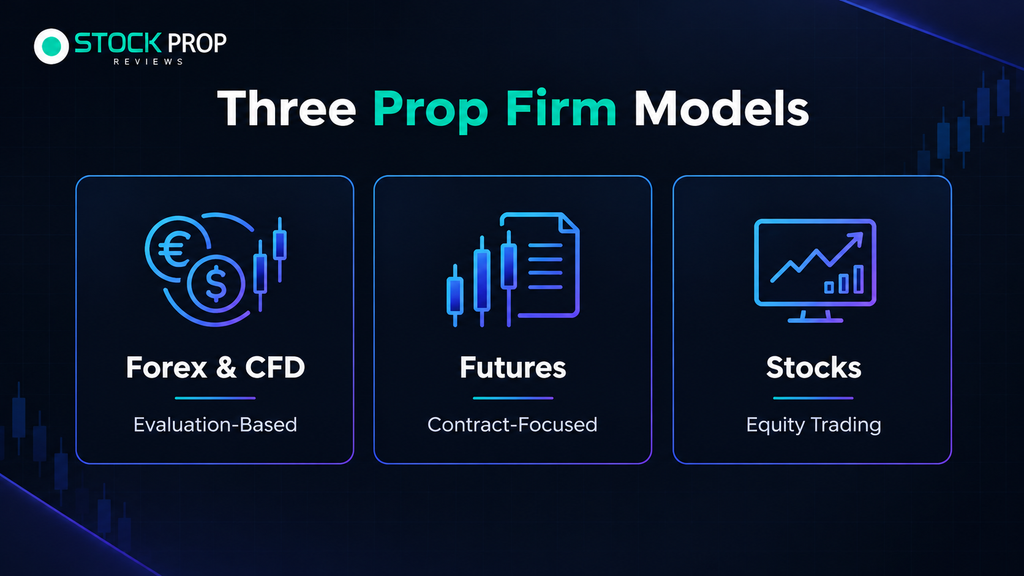
Different categories face different challenges, so traders should avoid assuming that all prop firms will follow the same path.
Challenge-Based Forex and CFD Firms
These may continue to thrive as evaluation programs allow traders to demonstrate that they can trade without using the full promised account balance.
However, companies competing almost entirely on cheap prices, large simulated balances, and a steady spate of promotions may find it hard to set themselves apart. They will survive on business expenses and customer retention and risk management and program quality.
Traders should remember that a simulated $100,000 account is not the same as $100,000 in cash. For example, with actual rules in effect, a 5% max loss of the original balances would assume a $5,000 loss allowance if done with the small account. There could be trailing drawdown calculations or other restrictions that alter the actual risk allowance that can be employed.
Futures Prop Firms
But futures-centric firms may even attract traders who prefer exchange-traded contracts and futures-only platforms.
Their viability will depend on the platform’s reliability, the pricing and data arrangements, and the rules of the sustainable program. Traders will also be concerned with contract details, tick sizes, commissions, and trading-session restrictions.
So a futures program isn’t more secure and transparent than a forex evaluation. It is contingent upon the conditions and could be appropriate or not.
Stock-Focused Prop Firms
Stock-based programs may appeal to traders who trade stocks and prefer stock-based rules over forex or futures.
They provide advantages in market access, trading structure, eligibility, risk controls, and reward terms. They also have to understand if it is a simulated or live activity and their legal relationship to the provider.
The best of this type are those that set out limits and provide guidelines that suit a style instead of maximum buying power.
What Competitors Often Miss About the Future of Prop Firms
Industry forecasts frequently ask whether prop firms will survive. Traders also need to know whether surviving firms will remain dependable and whether their programs offer a realistic fit for individual strategies.
Four distinctions are particularly important.
Industry survival does not guarantee trader success.
An individual trader may fail tests many times or be under bad rules, but a firm can remain in the black. The average customer doesn’t get paid for growing in the industry.
A successful payout does not prove long-term financial strength.
Good recent withdrawal experiences are good evidence, but winning a few payments does not prove solvency, nor does it guarantee future payment.
A generous profit split does not automatically mean better value.
Even programs that offer a generous payout may be unsuitable if they have different calculations for drawdowns or different rules for consistency or payout eligibility than a trader’s.
Simulated buying power is not personal wealth.
Traders generally do not own the account balance a program claims. They may be eligible for awards based on program terms, testing requirements, and compliance.
These issues are often more useful to a trader than predictions about which brand will dominate the market. An industry can become more professional without every provider becoming equally transparent or every program becoming more favorable to customers.
How Traders Should Prepare for 2027–2030
Traders do not have the power to determine the fate of surviving companies, but they can limit their exposure to business and contract risk beyond the necessary.
Before purchasing a rating, determine the total cost of participation. If an evaluation costs $100 and you purchase four attempts, it will cost $400 not including any other fees. If you fail an exam, do not expect to get a refund or reimbursement if you pass. Ask what the terms are.
Then, learn what it means to calculate a drawdown. So limit the open balance on a five percent loss on a $50,000 account, a loss of $2,500. If it’s just the “headline” percentage, beware of the real rules (trailing drawdown/equity limit) that can differ.
Your strategy also needs to be adequately served by the program. Scalpers may need predictable execution and reasonable transaction costs. Swing traders may require the ability to hold overnight or over weekends. A strategy that is fine in your brokerage account may be illegal in the prop firm.
Before committing money, check these essentials:
- Verify claimed regulatory approval and the company.
- Risk rules: Analyze the daily loss, max drawdown, prohibited strategies, and payout conditions.
- Payout history: Look for trustworthy, recent proof and the company’s response to unresolved complaints.
- Stability of operations: Look for platform quirks, policy changes, and reopened accounts.
- Financial Risk: Remove more than you can afford to lose when evaluating:.
Keep copies of the rules that applied when you purchased your challenge, maintain independent trading records, and avoid treating a simulated balance as guaranteed income.
TradeThePool and the Future of Stock Prop Trading
If you are a stock trader, not a forex or futures trader, programs that focus more on stocks may suit you best. In this category, one provider to look at is TradeThePool.
But take a look at its regulatory status. TradeThePool’s terms indicate that its evaluation is in a simulated trading environment. This stated term does not make it a government-regulated stock prop firm. Traders should not believe any claims to the contrary and should distinguish between company registration with any market authority, the firm’s choice to voluntarily certify a third party, and the decision to operate as a market-regulated firm.
Before paying for a given evaluation, review the program rules, eligibility, risk controls, and reward conditions. Documentation can assist you in evaluating a provider, but it won’t protect you from losing evaluation fees.
Get up to 10% off with our TradeThePool link. Please check the current offer and terms as these may change.
Common Trader Mistakes to Avoid
An improper choice of prop firm can cost three times the cost of a mistake.
Chasing the largest account: A larger advertised balance does not always mean a larger usable loss allowance. Start with the drawdown limits.
Assuming passing guarantees future rewards: If the trader is successful in his evaluation, he still needs to comply with rules, verification, and payout conditions of the program.
Ignoring operational warning signs: Exercise caution about mysterious payout delays, vague rule changes, and disregarded complaints. One complaint doesn’t always mean a company is failing, but a pattern should inform your decisions.
For further research, explore our : FTMO review, FundingPips review, prop firm comparison , and truth about funded trader lifestyle. These resources will help you compare business models and learn about the risks of their marketing promises.
FAQs
Will quoted firms cease to exist by 2030?
They likely won’t disappear entirely, but it’s not out of the question. More likely is consolidation, with some providers closing down, while others change their business models and practices.
Will prop firms face more regulation?
But the extent and timing of such scrutiny will vary with jurisdiction and business model. Traders should monitor the requirements and anticipate that not all firms will be regulated the same.
Which prop firms are going to survive?
Firms that have long-term viable businesses, where rules are law, where infrastructure is excellent, and where the payout process is well founded may find favor. This does not ensure survival or future payouts.
Are prop firms becoming more trader friendly?
Competition and looking to retain talent in the future may result in an increase in clarity of rules and support. But there will always be a trade-off between costs, business considerations, and risk. The improvements will likely not be consistent throughout the industry.
Should beginners try prop firms before 2030?
The first one to learn for beginners is repeatable strategy and risk management. Assessments are a disciplined method of testing trading discipline, but fees can pile up if a trader is not yet consistent.
Final Forecast: Fewer Firms, Higher Expectations
To conclude, prop firms will consolidate, enhance their technology, face government interference, and fight to retain traders between now and 2027-2030. Not going to die, but firms can bust/bankrupt or morph over the years.
Traders should care less about grand guessing games on what brands may win than on the business models and the terms of the contract in any particular case and the strategic compatibility.
In 2030, the winners might be those with solid operations, transparent governance, and a credible story about how they treat traders. But in the meantime, rigorous and scrupulous due diligence beats promising our industry’s future.